Homebuyer
Tax Reduction Scheme
Issued by Housing Authority
100% tax exemption on first €200,000 of sale price if leased to the same tenant 10+ years at affordable rent; 50% tax reduction if leased 3+ years. Applies only when landlord sells to their existing long-term tenant.
Tax break up to €200,000 when selling to your long-term tenant
You’ll be taken to the scheme’s official page.
Overview
The name suggests something broader than it is. This is not a general property tax break but a targeted incentive for one specific transaction: a landlord selling a long let, affordably rented home to the tenant already living in it. It also extends to properties the Housing Authority itself has rented under the Nikru biex Nassistu and Skema Kiri arrangements.
The logic behind it is worth understanding, because it explains why the conditions are as demanding as they are. Malta has a substantial stock of property caught in old rental arrangements, where a long standing tenancy at low rent leaves the owner with an asset they cannot easily realise and the tenant with a home they do not own. The scheme offers both sides a route out of that position, on terms that are meant to be fair to the owner rather than simply favourable to the tenant.
Who This Is For
Uniquely among these schemes, it serves both audiences at once, and by design neither party can use it alone. The tenant is buying the home they live in. The landlord is disposing of a rental property, and the relief applies to them too. Landlord and tenant must apply jointly and in solidum.
Eligibility
Full exemption from tax on the first €200,000 of the sale price requires two conditions to have held for ten years. The owner, together with any predecessor in title where the property was inherited, must have leased the property to the same tenant, or their predecessors where the lease itself was inherited, for that full decade at an affordable rent. And throughout those ten years the tenant must have remained eligible for the Housing Authority's Rent Benefit, meaning their income stayed below the threshold set in the relevant Government Gazette notice. The tenant must produce official documentation of their income across the whole ten year period.
A fifty per cent reduction works on the same principles over a shorter three year period, with three years of income documentation required instead.
Affordable rent is not left to interpretation. The Housing Authority sets specific monthly ceilings by locality group and by the number of bedrooms:
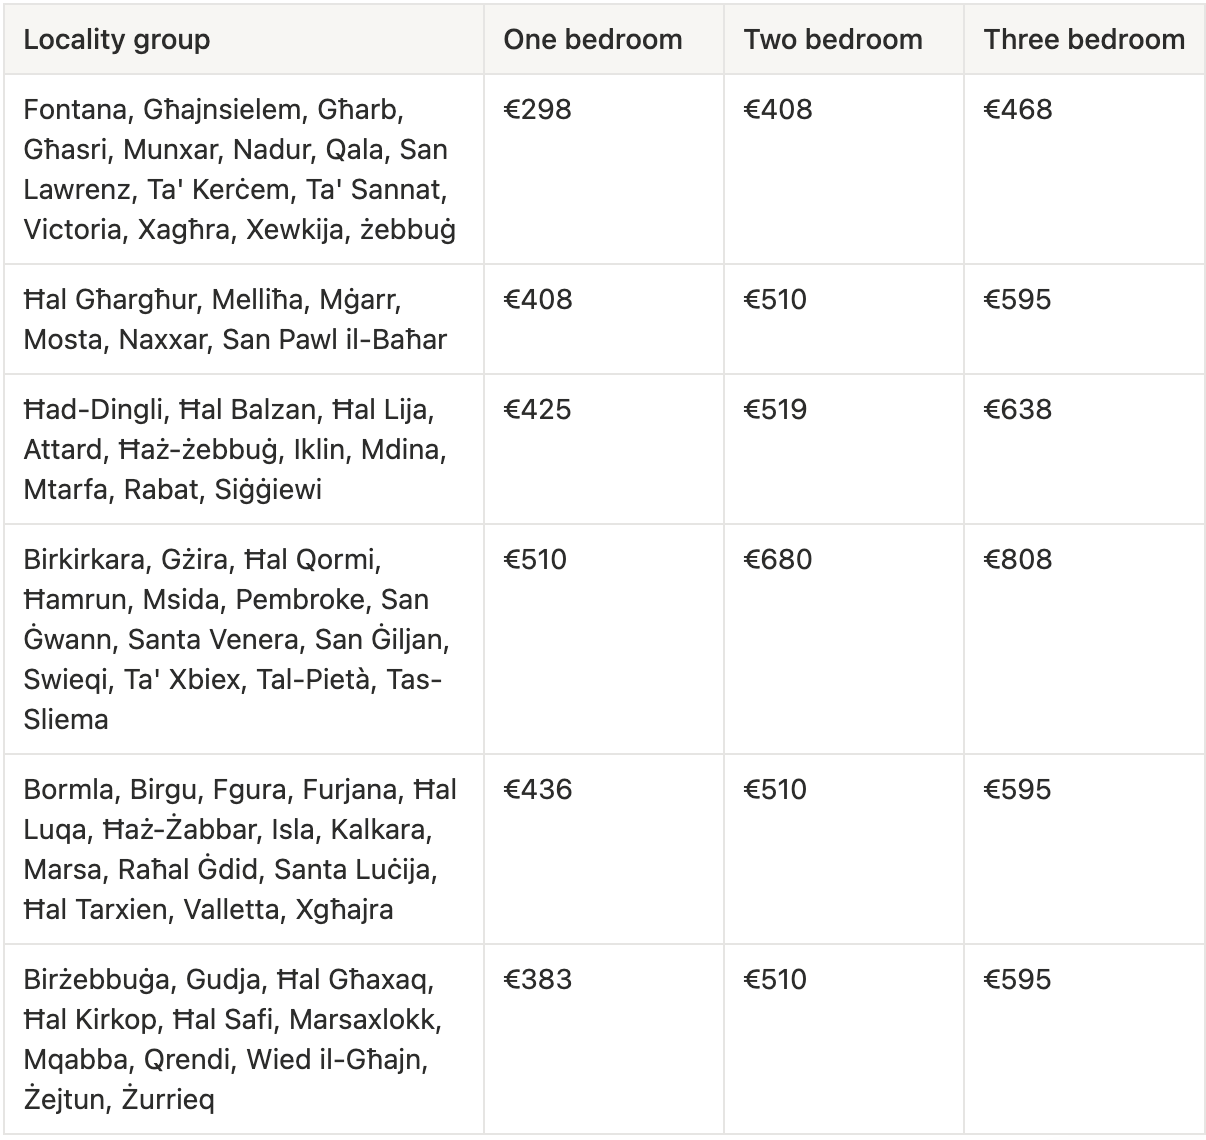
Applicants must submit an architect's certificate stating the property's size in square metres and its number of bedrooms, and the Authority reserves the right to place the property in a different size category if it falls short of the Planning Authority's guideline floor areas of 55, 90 and 115 square metres for one, two and three bedroom dwellings respectively.
There is a further provision for the oldest tenancies. Where a lease began before 1 June 1995, the children of the tenants may buy the property and benefit under the scheme, provided they lived with their parents for four of the five years before 1 June 2008.
What It Offers
A ten year affordable lease produces full exemption from tax on the first €200,000 of the property's price. A three year lease produces a fifty per cent reduction on the same first €200,000. In both cases the benefit applies to landlord and tenant alike on the transaction.
Applying
Two points of sequence matter here more than anything else in the scheme. The application must be submitted jointly, and it must be submitted before the promise of sale is signed. Applying afterwards is too late.
The Housing Authority then verifies that the tenant has genuinely lived in the property for the required period, that the landlord and tenant relationship has run for that period at an affordable rent, and that the tenant's income meets the criteria. It issues a certificate establishing the applicable percentage of tax rebate, valid for three years. The applicants present that certificate to their notary, who independently confirms its authenticity with the Authority before the deed proceeds, a safeguard built in specifically to prevent fraud.
Applications carry a €50 administrative charge.
How to Apply
Landlord and tenant submit a single joint application on the prescribed form, at the Housing Authority's offices at 22 Pietro Floriani Street in Floriana, at its Gozo branch in Victoria, or through the Housing Authority website.
What Can Block It
An application fails if the tenant's income exceeds the Rent Benefit threshold, if the tenant has not resided in the property for the required period, or if the rent charged does not meet the Authority's definition of affordable. It also fails where the tenant requires permission from the Minister responsible for Finance to acquire property under Chapter 246 of the Laws of Malta and has not obtained it, which is the point most likely to catch a non resident purchaser.
False declarations carry a fine at the Authority's discretion, a five year ban from every Housing Authority scheme, and the possibility of criminal proceedings.
Source & Verification
This summary draws on the Housing Authority's Tax Reduction Scheme page and its full Terms and Conditions, cross checked clause by clause and last verified on 4 August 2026.
- Scheme page: https://housingauthority.gov.mt/scheme/tax-reduction-scheme/
- Terms and Conditions (PDF): https://housingauthority.gov.mt/wp-content/uploads/2022/09/SCHEME-Rohs-fit-Taxxa-English.pdf
Disclaimer: This information is provided for general awareness only and does not constitute financial or legal advice. Schemes are reviewed and amended periodically, so availability, amounts, deadlines and eligibility criteria may have changed since this page was last verified. Always confirm current details on the official Housing Authority scheme page before applying or making any decision.